RSS

What AI Gets Right About the Toronto Market — and What It Can’t See

For most of the internet era, looking for a home meant the same ritual. Set the price cap, pick the number of bedrooms, check a few boxes, and scroll. Then the real work started: opening listing after listing, hunting for the detail that actually mattered.

That ritual is quietly giving way. A growing share of searches now begin as a conversation — someone typing “find me a home where my mother could live with us, near a park, under our budget” into an AI assistant and getting a real answer back. The shift is fastest among younger buyers. More Canadians under 30 now turn to tools like ChatGPT for financial and mortgage advice than to a licensed broker or advisor.

The platforms have moved with them, here in Canada. In June, Royal LePage launched an app built around conversation instead of filters, with instant AI summaries of listings and an assistant available around the clock in 22 languages. In May, Zealty became the first Canadian listing portal to put live listings directly inside ChatGPT. Zillow did the same thing in the American market last fall. Across the industry, the conversation is now where the search starts.

It’s a real shift, roughly the size of the move from newspaper listings to online portals a generation ago. It’s also, in most respects, making the early part of a home search genuinely easier.

But there’s something about this market specifically that no national article will tell you. How well these tools serve you in Toronto depends almost entirely on which Toronto you’re shopping in.

What AI Is Genuinely Good At

Treated as a research assistant, AI is excellent at the wide-open early stage of a search.

Start with the search itself. You no longer have to translate your life into filter categories. You can describe the life and let the machine do the translating. “We need room for a home office, my in-laws stay for a month every winter, and I can’t do a long commute” is now a workable query. Better still, the conversation continues from there. More like this one, but with a yard. What’s the trade-off between these two. Which one’s the shorter drive downtown. The sifting that used to cost a lost Saturday, the machine now does in a few minutes.

It’s also a patient explainer. Conditions, deposits, land transfer tax — and in this city, the second one, because Toronto charges a municipal land transfer tax on top of the provincial one — the stress test, fixed versus variable. You can ask what any of it means at midnight without feeling like you’re asking a foolish question, and keep asking until it’s actually clear.

And it’s quick with the arithmetic that used to slow everything down. Canadians are already leaning on it here: in CMHC’s most recent Mortgage Consumer Survey, one in six people who researched their mortgage online used AI to do it. Rough payment scenarios, or what a renewal at today’s rates does to a monthly budget, used to take a spreadsheet and an afternoon. Now they take minutes, which means you can test more possibilities before committing to any of them.

That early phase — figuring out what you want, what it costs, and where to look — is real work, and it moves dramatically faster than it did two years ago.

What it means for you: use AI to arrive at the conversation informed. It’s very good at getting you to the right questions.

The Two Toronto Markets It Handles Very Differently

Here’s the part that matters most in Toronto.

AI is at its best where inventory is deep and homes are broadly comparable, because that’s where the data actually supports a confident answer. It’s at its weakest where supply is thin and every property is different.

In the GTA, those two conditions describe two different markets that happen to share a map.

At the end of August, there were 7,882 condo apartments listed for sale across the region, against 1,330 sales that month. In Toronto Central alone, condo apartments made up roughly 70% of everything on the market. That’s a deep, well-documented pool of broadly similar units, and an AI comparing a one-bedroom on one floor to a one-bedroom three floors up will usually get within range. Useful, and reliable.

Now the other market. In August, GTA semi-detached homes and freehold townhouses had under three months of supply at the current pace of sales. In the City of Toronto, semis sold at 100% of asking in an average of 27 days. That’s a thin market of homes that aren’t comparable to each other in the ways that matter — lot width, position on the street, what was done to the basement, whether the third bedroom is a real bedroom. There’s far less data, and far more of the value sits in things no dataset records.

I’ve watched both ends of this. A listing of mine in Richmond Hill, above $2.5 million, sat for six months and barely drew showings until we reduced the price meaningfully. It was one of the most beautiful homes I’ve represented. In the same stretch, buyer clients of mine in Swansea were one of seventeen offers on a property. Same region, same year, opposite realities. Not because one home was better. Because one pocket had a glut of supply and the other had almost none.

An AI reading both addresses would have priced them from the same regional averages and been wrong twice.

What it means for you: the more unique your property or your target neighbourhood, the less you should trust a machine-generated number, and the more the local read is worth.

Where AI Gets It Wrong — and How to Catch It

AI’s failure mode is being confidently wrong. It delivers a mistake in the same fluent, assured tone as a fact, and it doesn’t flag when it’s guessing.

Sometimes that is hallucination, the industry’s word for AI inventing things — details, listings, whole answers that sound polished and specific and simply aren’t true. Sometimes it’s just stale information: a comparison built on a home that sold three weeks ago.

Then there’s the second category, and it matters more. The things it can’t see at all.

Condition. It can’t see the true state of a home, or of the comparable sales its pricing quietly rests on.

Feel. It doesn’t know how a street lives — what it sounds like at rush hour, how it feels on a Saturday morning.

School catchments. In this city, one side of a street can feed a different school, and reputations shift with a principal. Map data doesn’t carry that.

Position. A corner lot and a home tucked into the end of a cul-de-sac can carry very different value. AI reads them as the same address.

What hasn’t been announced yet. The site down the block that is likely to be developed, the rezoning still circulating at city hall, the transit alignment everyone in the neighbourhood is talking about and no dataset has recorded. These shape future value, and they live in local knowledge.

Those are examples, not the whole list. Every neighbourhood carries its own intangibles. No portal has a column for them.

None of this makes AI the wrong tool. It makes verification part of using it properly. Treat its answers as leads rather than conclusions, and check anything you’d act on against the live listing, the paperwork, or someone who has actually been inside.

What it means for you: you wouldn’t make one of the largest financial decisions of your life on a single unverified source in any other context. This is no different.

Selling? Your First Showing Is Now to a Machine

If you’re on the other side of the transaction, this reaches you in a way most sellers haven’t considered. Before a buyer ever sees your photos, an AI may have already read, summarized, and ranked your listing.

When an app hands a buyer an instant summary of your home in any of 22 languages, software is doing the first sort. In a region as multilingual as this one, that’s not a small feature. Your home either surfaces in that conversation or it doesn’t, and what decides it is substance: the real upgrades, the real layout, the real numbers. Specific, accurate details are what a machine can find and repeat. Vague lifestyle copy is what it skips.

It also means your photos and your facts have to agree. An AI summary will amplify an inconsistency a human browser might have skimmed past. And pricing correctly matters more than it used to, because a mispriced home gets filtered out of conversations it never knew were happening.

That last point matters more right now than it did a year ago. With listings down 14.1% year-over-year across the GTA in August and TRREB flagging that less choice and more competition “could ultimately result in renewed price growth in the months ahead,” well-prepared homes are being found. Poorly presented ones are being sorted out earlier, and more quietly, than before.

What it means for you: ask whoever lists your home how it will read to both audiences — the buyer, and the machine briefing the buyer.

What Hasn’t Changed

AI is at its best in the research phase: gathering, comparing, explaining, estimating. The decisions that determine how the whole thing turns out — what to offer, how to negotiate, when to walk away, how to price — are a different kind of work, and they still come down to judgment.

Pricing strategy, offer strategy, and negotiation are calls built on local, current, in-person knowledge. AI can assist the analysis. It’s never walked the block at six in the evening, stood in the basement, or heard what the neighbours said at the open house. A home purchase is also a life decision with a financial decision inside it, and a chatbot handles neither part well.

There’s one more thing worth knowing. AI guidance isn’t regulated the way advice from a licensed professional is, and most Canadians don’t realize it — fewer than half know that a chatbot’s advice carries none of the oversight a licensed advisor’s does. In Ontario, a registered real estate professional answers to RECO under provincial legislation, carries obligations to you, and is accountable for what they tell you. A chatbot is none of those things.

That’s not a reason to avoid the tools. It’s the reason most buyers and sellers still put a professional between the research and the decision.

What it means for you: an agent’s real edge is precisely the list of things AI can’t see.

The Smart Way to Run an AI-Assisted Search or Sale

Put it together and it’s a simple division of labour.

If you’re buying: use AI to sharpen your wish list, learn the vocabulary, rough out affordability, and build a candidate list. Then bring that homework to someone who can verify it, tour it with you, price it, and negotiate it. And weight your confidence by segment — if you’re shopping condos, the machine is on solid ground; if you’re shopping freehold in a tight pocket, treat every number it gives you as a starting point.

If you’re selling: ask how your listing reads now, to buyers and to the machines summarizing it for them, and make sure the details and the price survive both audiences.

Either way, what AI buys you is speed, clarity, and convenience. Answers in minutes instead of weekends. A complicated process explained in plain language. Help available whenever you happen to be thinking about it.

Start With the Machine. Finish With a Person.

I use these tools. I’m not going to pretend otherwise, and I wouldn’t want an agent who refused to. What I’m careful about is the handoff — knowing exactly where the research ends and the judgment begins.

The market-wide story is the easy part. You can read it, and now you can ask a machine to summarize it for you in whatever depth you like. The part you can’t Google, and the part no assistant can generate, is what it all means for your postal code, your property, and your timeline.

That’s the part I handle. I arm you with the information, the statistics, and the nuances, so that the decision — and it’s always your decision — is an informed one.

If AI has been part of your search, or you’re wondering how your home would look through its eyes, bring me what the chatbot told you. I’ll tell you what it got right.

Sources

1. Market Watch, August 2026 — Toronto Regional Real Estate Board (TRREB)

2. More Young Canadians Now Use AI Than Licensed Brokers for Financial Advice — REMIC / Abacus Data, July 20, 2026

3. Royal LePage reimagines how Canadians search for properties with the launch of its new AI-powered mobile app — Royal LePage, June 29, 2026

4. Zealty Becomes First Canadian Real Estate Platform Inside ChatGPT — Fintech.ca, May 25, 2026

5. Zillow becomes the only real estate app in ChatGPT — Zillow, October 6, 2025

6. 2026 Mortgage Consumer Survey — Canada Mortgage and Housing Corporation (CMHC)

Read

2026 Mid-Year Check-In: What the First Half Tells You About Your Next Move

For two years, most people watching the Toronto market have braced for one of two dramatic endings. A deeper slide, or a rate-cut-fuelled boom. Buyers waited for prices to fall further. Sellers waited for 2022 prices to come back. Everyone waited for a signal.

Neither ending arrived.

The market didn't crash, and it didn't take off. It did something harder to notice. It started to settle. The pace of the price decline is easing. Activity picked up as a delayed spring finally arrived. And for the first time in a while, the second half of the year looks like something you can actually plan around.

Let me be clear. A few modest months don't make a boom, and stabilizing is not the same as a comeback. But a market finding its footing is genuinely useful news. It's just quiet news.

Here's what the first half of 2026 tells us — and what it means whether you're buying, selling, renewing, or simply watching.

Buyers and Sellers Are Finally Speaking the Same Language

For a long stretch, the defining feature of this market was the standoff. Sellers priced for yesterday's market. Buyers offered for tomorrow's. Nothing moved.

That gap has been closing, and here in the GTA the reason is simpler than most forecasts made it sound. The direction is becoming clear. Prices are still down from a year ago, but the pace of the decline is easing, and the board now expects it to flatten. As TRREB President Daniel Steinfeld put it in the July release, "if current trends continue, home prices could start to level off compared to last year." When the direction stops being down, waiting stops paying.

The activity backs it up. GTA home sales strengthened through the spring — up 6.3% year-over-year in May and 9.4% in June — as a late-starting spring market finally arrived. July cooled slightly, down less than 1% from a year earlier, but that pause came with a twist worth understanding.

Even as sales flattened in July, the market kept tightening — because listings pulled back faster than buyers did. New listings fell 12.9% year-over-year in June and 17.8% in July, and active inventory is down about 12%. Fewer homes, roughly the same number of buyers. That's why TRREB flagged that, with sales taking a larger share of listings, buyers "may find there is less room to negotiate moving forward."

Prices are telling a steadier story than the headline suggests. The average selling price is still down year-over-year, but the MLS Home Price Index — which compares similar homes over time — has seen its annual decline narrow three months running: 6.7% in May, 5.4% in June, 4.6% in July. The drop isn't over. But it is clearly slowing.

And this is not a market with a glut of listings. At about 4.6 months of inventory, with homes across the GTA selling at 97% of asking, conditions are balanced and tilting toward tight — not the deep buyer's market some are still waiting for.

What it means for you: the shift isn't about who "won." It's that the uncertainty is clearing, and the direction is finally something you can plan around.

The Renewal Wave and What It Means for Your Home

The headline rate has gone quiet. The Bank of Canada held its policy rate at 2.25% again in July — another hold, not the rate cut some were hoping for. Its July outlook has inflation easing gradually back to around 2% by early 2027, which is another way of saying nobody is forecasting drama in either direction. A steady rate, whatever its level, is something you can plan around. That's more than we could say for most of the past four years.

For millions of households, though, the rate that matters this year is the one on the renewal letter, not the one announced eight times a year.

Canada is deep into the renewal wave — the large cohort of mortgages signed at the ultra-low rates of the early 2020s now coming up for reset, and it still dominates the mortgage market. More than 1.5 million households have already renewed at higher rates, and roughly another million will sign new terms over the coming year.

The shock has landed softer than the forecasts warned. About 60% of households renewing across 2025 and 2026 are seeing their payment rise, but close to a quarter are seeing it fall. The increases are shrinking, too. Those renewing in 2026 are looking at roughly 6% more than they paid at the end of 2024, against about 10% for the 2025 group. The steepest jumps sit with five-year fixed holders, up 15 to 20% on average, while many variable-rate holders are paying less than they were.

If your renewal is coming up, you have real options, and a good mortgage broker can walk you through them: shopping the renewal instead of signing the first offer, adjusting your amortization, weighing a shorter or longer term. Start that conversation early, not in the last week before you sign.

A renewal is also more than a mortgage question. For a lot of households, it's the moment the bigger question finally surfaces: does this home still fit? People reach their renewal and realize the place they bought in 2021 doesn't match the life they're living in 2026. The commute changed. The family grew. The space stopped working. Rightsizing is a legitimate answer to a renewal.

What it means for you: find out what your home is worth before your renewal conversation, not after. It's the number every other option depends on.

What the Headline Numbers Can Miss

One caution about everything above. Headline averages are a blend, and blends can mislead.

Here's a clean example from right here at home. The GTA average selling price fell from about $1,058,700 in June to $1,003,900 in July — a move that looks alarming until you see what's underneath it. A good part of that month-to-month drop was mix: fewer high-end detached homes changed hands in July, which pulls the average down even when individual homes haven't lost that value. On a like-for-like basis, the Home Price Index's annual decline actually eased over the same stretch. The raw average and the real trend were pointing in different directions.

The same blending hides the differences that matter most. In July, GTA condo apartment prices were down just 2.3% year-over-year — the most resilient of any home type — while freehold semi-detached prices were off 7.4%. Same market, same month, opposite stories. A condo and a house in the very same Toronto neighbourhood can be in completely different phases of this market at the same time.

This is what I mean when I say real estate is micro, micro, micro specific. The GTA-wide number can tell you the climate. It can't tell you whether your neighbourhood, your property type, or your timeline favours acting or waiting this season.

What it means for you: use the market-wide update to understand the climate. Use a local read to make the decision.

What It Means for You — Buyers, Sellers, and Renewers

A stabilizing market rewards preparation over prediction. What that looks like depends on whether you're buying, selling, or renewing.

If you're buying: the fear of buying right before another drop is fading — the decline is slowing, not accelerating. You can act on your life instead of your fear. But leverage isn't automatic anymore, and with listings pulling back, the room to negotiate is narrowing. Financing and inspection conditions are back on the table for now — use that while it lasts.

If you're selling: the buyers are back, but they're informed and unhurried. Pricing to this market — not the one from three years ago — is what separates the homes that sell from the homes that sit. With fewer listings competing, well-priced, well-presented homes are moving.

If you're renewing or staying put: treat the renewal like the financial event it is. Start early. Know your home's current value. It's the anchor for every option you have, from renegotiating to refinancing to rightsizing. Even if your renewal is years away, a calmer market is a good moment for an equity check-in and an honest "does this home still fit?" conversation. TRREB expects more competition among buyers in the second half of the year, and eventually renewed price growth — which means this planning window stays open, but it won't stay this open forever.

Across all three: the second half favours people who know their local numbers and their own timeline, not people waiting for a market-wide signal. Stability doesn't pick winners. Preparation does.

The Second Half Belongs to the Prepared

That's the mid-year picture. Prices showing signs of finding their footing. Buyers and sellers meeting closer to the middle. Renewal timelines quietly becoming the most important date in many households' financial year. And meaningful differences hiding beneath the GTA-wide headline.

For the first time in a while, this is a market you can plan in rather than brace against. The market-wide story is the easy part — you just read it. The part you can't Google is what it means for your postal code, your property, and your renewal math.

That's the part I handle. I arm you with the information, the statistics, and the nuances, so the decision — and it's always your decision — is an informed one. If you're wondering what this market means for your situation, whether you're thinking about buying, selling, or your renewal is coming up and you want to know where your home's value stands, that's exactly the kind of conversation I'm glad to have. No pressure.

Sources

1. Market Watch, May–July 2026 — Toronto Regional Real Estate Board (TRREB)

2. Bank of Canada maintains the policy rate at 2¼% (July 15, 2026) — Bank of Canada

3. Renewal wave peaks but still dominates mortgage market — Canada Mortgage and Housing Corporation (CMHC)

4. Mortgage renewal wave strains some regions and borrowers — CMHC

5. How will mortgage payments change at renewal? An updated analysis — Bank of Canada

Read

What You Can Actually Negotiate When Buying a Home (It’s Not Just the Price)

When most people picture negotiating on a home, they picture one number. The list price. You offer under asking, the seller counters, you meet somewhere in the middle, and whoever gives up the most ground “loses.”

That back-and-forth over price is what most buyers think of as the negotiation.

It’s a fraction of it.

The price is the headline. The real negotiation happens in the terms underneath it — and in 2026, those terms matter more than they have in years. The market has rebalanced. Nationally, inventory sat at about 5.2 months at the end of April, close to its long-term average and squarely in balanced territory.1 Neither side holds the kind of leverage sellers had a few years ago. For buyers, that is real room to negotiate that simply wasn’t there during the bidding-war years.

Here is what separates the buyers who come out ahead. It isn’t the ones who push hardest on price. It’s the ones who understand everything that’s available to them, and know which of it is worth asking for.

The Price-Only Trap

It’s easy to assume a seller cares about one thing: the highest possible number. In practice, most care about more. They care about certainty — whether the deal will actually close. They care about timing. They care about whether your financing comes together, or falls apart halfway through.

That’s good news for you, because it means you have more to work with than a single figure. When we treat an offer as a package — price, terms, timing, and conditions, all together — we can often build a better outcome than a buyer who just hammers on price. It’s why a clean, well-structured offer can beat a higher one. To the right seller, certainty is worth more than the extra dollars.

So before you anchor on a number, look at the whole picture. Here’s what else you can shape.

The Money That Never Touches the Price

Some of the most valuable things you can ask for don’t change the sale price at all. They change what the deal actually costs you.

Start with a seller concession. In a balanced market, sellers are more willing to give one — a straight price reduction, or agreeing to cover certain costs to get the deal across the line.2 It’s worth asking for any time the upfront cash is your tightest constraint. (You may have read about U.S.-style rate buydowns, where a seller pays to lower your mortgage rate. They exist here, but they’re far less common, and our five-year renewal cycle blunts the benefit — any rate advantage resets at renewal. With five-year fixed rates already near 4%, the math rarely works the way it does south of the border.3)

The bigger money story in Canada is usually on your side of the table, in the costs you can offset. Closing costs here include Land Transfer Tax, which can run into the thousands. But first-time buyers can recover meaningful rebates: up to $4,000 provincially in Ontario, with the City of Toronto adding more on top.4 And tax-free tools like the First Home Savings Account let you set aside up to $40,000 toward your purchase.5 Knowing which of these you qualify for can outweigh a modest price cut. It’s exactly the kind of detail I walk my clients through before we ever write an offer.

The Inspection Is Your Second Negotiation

In Canada, a lot of the real negotiating happens through your conditions. After years of buyers waiving conditions to win bidding wars, conditional offers are making a comeback as the market rebalances.2

A home-inspection condition gives you a window — usually five to ten business days — to have the home professionally inspected. An inspection on almost any home turns up something worth addressing. When it does, you have a fresh round of leverage. You can ask the seller to make the repairs. You can ask for a price reduction or a credit so you can handle them yourself. Or, if the issue is serious enough, you can walk away. Pair it with a financing condition, so your mortgage is fully approved before the deal goes firm.

A few rules I give my clients. Focus on what genuinely matters — health, safety, and the big-ticket systems like the roof, the furnace, the foundation — rather than nickel-and-diming every cosmetic flaw. And treat the report as a planning tool, not just a bargaining chip. An aging furnace isn’t necessarily a deal-breaker. It’s a heads-up that helps you budget.

Terms and Timeline: The Wins That Aren’t About Money

One of the most powerful levers costs you nothing. Flexibility. To a seller, time is often worth as much as dollars.

Say the sellers need a few extra weeks before they hand over the keys, because their next place isn’t ready. A flexible closing date — or a short post-closing occupancy, a rent-back, that lets them stay on for a bit — can make your offer the one they choose. Your deposit matters too. A strong, well-structured deposit signals you’re serious and your offer is solid. The closing date, the length of your conditional period, and how your deposit is framed are all things we can shape to fit what the seller needs.

The move is simple. Give the seller the timeline they need, and you’ll often get the terms you want in return.

What Actually Comes With the House

This is the simplest ask of all, and the one buyers most often forget. In Canada, it comes down to two words: chattels and fixtures.

Fixtures are attached to the home — built-in shelving, light fixtures — and they generally stay unless the seller specifically excludes them. Chattels are movable — the fridge, the washer and dryer, the patio set — and they don’t come with the home unless they’re named in the Agreement of Purchase and Sale. So, if you want them, ask, and get them written in. Spell out exactly what stays, right down to the make and model on the big-ticket items, so there’s no dispute on closing day.

And if there’s something you love, ask for it. The worst answer you’ll get is no.

Putting It All Together

Knowing what’s negotiable is the easy part. Using it well is what turns a list of asks into a better deal.

The buyers who succeed don’t fire off every possible demand at once. They lead with what the seller values most. They structure their conditions thoughtfully. They avoid the pile-on of small requests that makes a seller dig in. Above all, they read the seller’s real motivation — and that’s where a sharp broker earns their keep, negotiating the price, the conditions, the chattels, and the timeline as one strategy.

A calm, well-prepared buyer almost always does better than an aggressive one. The goal isn’t to beat the seller. It’s to structure a deal that works for both sides — and to make sure you’re not leaving value on the table you never knew was there.

That’s the value of a broker who treats your offer as one strategy, not a single number. I arm you with the information, the statistics, and the nuances. The decision is always yours; my job is to make sure it’s an informed one.

If you’re getting ready to buy, this is exactly the kind of conversation worth having before you write an offer. I’d be glad to walk through everything you could be asking for in your situation. No pressure. Just a clear picture.

Sources

  1. CREA — National Statistics (balanced market, April 2026)

  2. RE/MAX Canada — How Conditional Offers Are Making a Comeback

  3. Ratehub — Best 5-Year Fixed Mortgage Rates, Canada

  4. Deeded — First-Time Home Buyer Incentives in Ontario 2026

  5. Canada.ca — First Home Savings Account (FHSA)

Read

House Hacking in 2026: What the Hype Got Wrong — and What Actually Works

If you've spent any time on real estate TikTok in the last few years, you've probably seen the house hacking pitch. Buy a property, rent part of it out, let your tenants cover the mortgage. Live for free. Build wealth while you sleep.

It sounds like the kind of thing that works great in a YouTube thumbnail and falls apart in real life. And honestly? Sometimes it does.

But here's what those videos usually get right even when they oversell the outcome: housing costs have outpaced wage growth by a wide margin, and for the right buyer, generating income from a property can make ownership viable when it otherwise wouldn't be. The strategy is real. The "living for free" part is just the clickbait version of it.

In 2026, the smarter question isn't whether house hacking works — it's whether it's the right fit for you, your market, and your numbers.

Here's what that actually looks like.

What House Hacking Actually Means

House hacking is straightforward in concept: buy a primary residence and generate income from it to help offset the cost of owning it. The definition is that simple. The execution has a lot of range.

The term got a lot of breathless social media attention a few years ago — often paired with promises of "living for free" or "having your tenants pay your mortgage." That framing wasn't entirely wrong, but it oversimplified things in ways that set some buyers up for disappointment. In 2026, the more useful way to think about house hacking isn't about eliminating a housing payment. It's about engineering a more manageable one.

If a secondary suite generates $1,600 a month and the mortgage is $3,800, that $2,200 net payment might be very achievable where $3,800 wasn't. That's the real value — not a free house, but a door that was otherwise closed, now open.


The Most Common Ways Buyers Are Doing It

The Secondary Suite Boom

Secondary suites — basement apartments, laneway houses, garden suites, in-law suites — have become the gold standard of modern house hacking in Canada, and the federal government has made significant moves to support them.

The Canada Secondary Suite Loan Program, administered through CMHC, now offers homeowners up to $80,000 at a fixed rate of 2% over a 15-year term to build or convert a secondary suite — double the program's original limit.¹ For buyers who need more borrowing power, CMHC's refinancing program allows homeowners to access up to 90% of their home's post-renovation value, which opens up more ambitious projects than a standard refinance would allow.²

Secondary suites have also become increasingly legal in places where they weren't before, as cities across Canada work to meet provincial housing targets. That regulatory tailwind, combined with federal financing support, makes this the most accessible entry point into house hacking for most buyers.

Multi-Generational Living

House hacking isn't always about renting to strangers. For a growing share of buyers, it means sharing a home — and the costs that come with it — with family.

Multi-generational buying has been climbing steadily in Canada, driven by a convergence of forces: an aging population, affordability pressure that makes independent household formation increasingly difficult for young adults, and immigration patterns that prioritise family reunification. According to Statistics Canada's 2021 Census, the number of multi-generational households in Canada grew 21.2% over the preceding decade — more than twice the overall rate of household formation.³ That structural shift has only accelerated since.

For families where the goal is housing an aging parent or a family member with a disability, there's an added financial incentive worth knowing: the federal Multigenerational Home Renovation Tax Credit provides up to $7,500 for constructing a self-contained secondary suite for a qualifying senior or adult. It's a meaningful offset on a renovation that was likely happening anyway.¹

The Classic Multi-Family

Buying a duplex, triplex, or small multi-family property and living in one unit while renting the others is the original form of house hacking — and it still works in Canada. CMHC mortgage insurance allows buyers to purchase owner-occupied properties with as little as 5% down on homes up to $500,000, with the minimum down payment sliding to 10% on the portion between $500,000 and $999,999.² As of December 2024, the insured mortgage ceiling was raised from $1 million to $1.5 million, opening the door to more buyers in higher-priced markets.¹

For those willing to share a property line with their tenants rather than just a backyard, the income potential is typically higher than a single secondary suite, and the strategy is time-tested.

The Honest Math

Here's the honest truth about house hacking in 2026: the "living for free" narrative that circulated on social media was never universally achievable, and it's even rarer now. Interest rates have come down from their peak but remain elevated compared to the pandemic-era floor. Home prices, while not climbing at the same frenetic pace as a few years ago, are not meaningfully lower in most major markets.

That's not a reason to dismiss the strategy. It's a reason to recalibrate expectations.

The goal in 2026 isn't to eliminate a housing payment. It's to reduce it to something sustainable. In many cases, a well-chosen house hack turns an unaffordable property into a manageable one — and that's a significant win. Buyers who run realistic numbers, factor in vacancy periods and maintenance costs, and approach the strategy with patience tend to do well. Buyers who chase optimistic projections tend to struggle.

Canadian lenders have also adapted. Rental income from owner-occupied multi-unit properties can be factored into qualifying income, subject to lender-specific guidelines and CMHC rules. The rules exist to keep the qualifying process grounded in real data — they're a reasonable safeguard, not a barrier.


Who This Works Best For

First-time buyers facing an affordability gap. If income doesn't support the mortgage on a home that checks all the boxes, a property with rental potential can bridge that gap — both by reducing the net monthly payment and, in qualifying scenarios, by improving what a lender will approve in the first place.

The sandwich generation. Gen X buyers — often supporting aging parents while still raising or housing adult children — have more motivation than any other group to maximise what a home does for them. A property designed for multi-generational living isn't just a financial strategy; it's a practical solution to a real caregiving reality. For families navigating the specific situation of housing a senior parent or a family member with a disability, the Multigenerational Home Renovation Tax Credit makes the financial case even stronger.¹

Future investors learning the ropes. Living in a property while managing a rental unit is one of the best ways to learn real estate investing without the full risk exposure of a standalone investment property. A buyer who spends two or three years in a house hack and then moves to their next home can keep the first property as a full-time rental — with tenant management experience already under their belt.

What to Know Before Getting Started

Zoning and local regulations are non-negotiable. Secondary suite legality, short-term rental rules, and multi-family zoning vary dramatically by municipality. What's permitted three blocks away may not be permitted on the property being considered, and the rules are changing quickly as cities work to meet provincial housing targets. Unpermitted suites create liability headaches that outlast the savings they generate. Doing things by the book from the start isn't just the right approach — it's the only one that holds up over time.

Run conservative numbers. Plan for vacancies. Budget for maintenance. Use realistic rent estimates based on comparable properties in the neighbourhood, not best-case scenarios. If the math still makes sense when accounting for a month or two of vacancy each year plus routine repairs, it's a solid plan. If it only works at 100% occupancy with top-of-market rents, it's a risk.

Be honest about lifestyle fit. Sharing a property with tenants — whether strangers renting a basement suite or family members in a multi-generational setup — comes with real tradeoffs. It requires a certain temperament and a willingness to handle the occasional uncomfortable conversation. Buyers who go in with clear boundaries and realistic expectations tend to thrive. Those who underestimate the interpersonal dimension often don't.


The Bottom Line

House hacking is no longer a fringe idea for real estate investors. It's a mainstream strategy that serious buyers in 2026 are using to navigate a market that doesn't hand out easy answers. The fundamentals of homeownership — building equity, gaining stability, and creating long-term wealth — still hold. House hacking simply acknowledges that the path to those benefits sometimes requires a little more creativity with how a property is used.

Every neighbourhood is different. Zoning rules, rental demand, and property potential vary widely, and the right house hack for one buyer might look completely different for another. If you're wondering whether you're the right fit for this strategy, that's exactly the conversation worth having. Reach out and let's dig into what it could actually look like for your market and your numbers.

Sources:

  1. Government of Canada – Canada Secondary Suite Loan Program / Multigenerational Home Renovation Tax Credit: https://www.canada.ca/en/department-finance/news/2024/12/2024-fall-economic-statement-making-it-easier-for-homeowners-to-build-secondary-suites.html

  2. CMHC Refinance for Building Secondary Suites / Homeowner Mortgage Loan Insurance: https://www.cmhc-schl.gc.ca/professionals/project-funding-and-mortgage-financing/mortgage-loan-insurance/mortgage-loan-insurance-homeownership-programs/refinance

  3. Statistics Canada, 2021 Census of Population – Multigenerational Households: https://www.statcan.gc.ca/en/subjects-start/housing

Read

2026 Home Design Trends: What's In, What's Out, and What Buyers Are Responding To

After a decade of cool grays, crisp whites, and spaces that looked more like showrooms than homes, buyers have changed what they're looking for. Call it quiet luxury — the idea that richness comes from depth, craft, and intention rather than flash and excess. It's not maximalism. It's a shift toward spaces that feel like somewhere you'd actually want to live.

That shift is showing up in buyer data, listing descriptions, and design reports across the board. Here's what it looks like in practice — and what it means if you're thinking about selling your home.

What's In

Color Is Back — And It's Warmer Than You Think

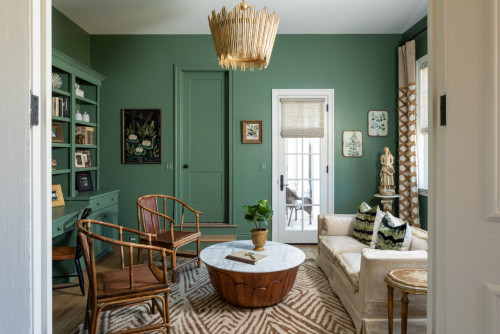
The all-gray interior isn't just tired. Buyers have moved on. The biggest shift in Zillow listing descriptions over the last year has been a surge in "color drenching" — coating walls, ceilings, and trim in a single immersive hue — up 149% year over year.1 The direction is consistent across paint brands and design reports: warm beiges, caramels, terra cotta, sage green, and soft navy. A mix of '70s sunbaked tones and calming naturals.3

The psychology behind it makes sense. Buyers are increasingly seeking homes that feel like a sanctuary, not a showroom, and warm cohesive color is one of the fastest ways to create that. If you're thinking about selling your home, this has a practical implication: a single well-chosen paint refresh can dramatically change how a space photographs and how it feels at first walk-through.

The Art Deco Revival: Details That Stop the Scroll

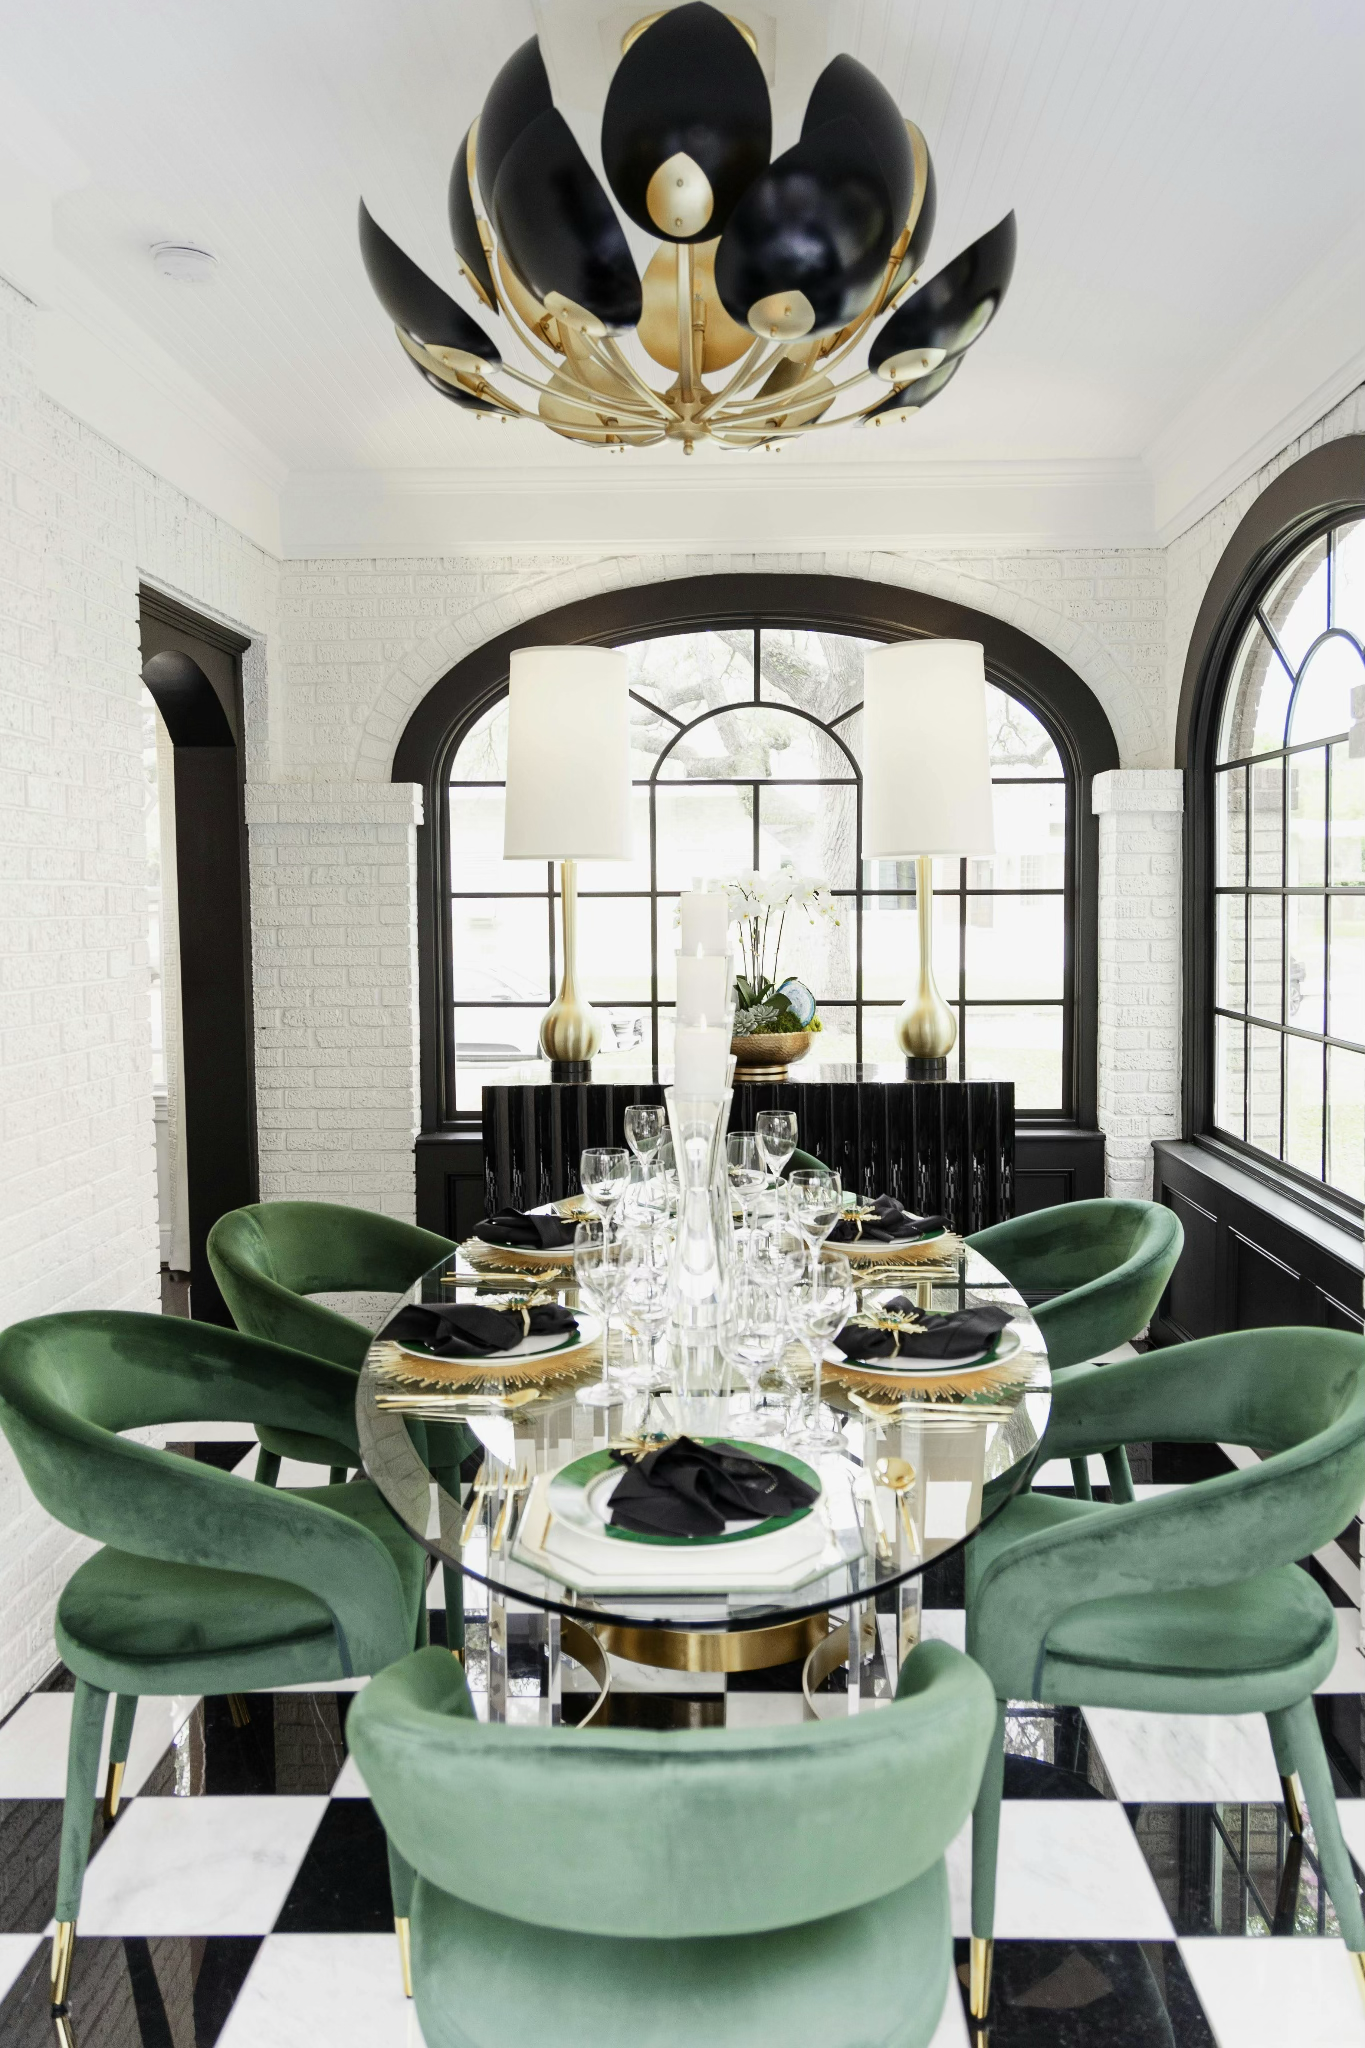
Buyers are actively looking for character — and that's showing up clearly in what design platforms are tracking. Houzz flagged the Art Deco revival as one of the defining trends of 2026, with searches for Art Deco interiors up 22% year over year.2 Think chevron patterns, brass accents, jewel tones, curves, arches, and scalloped edges that soften spaces and add visual depth. Listing mentions of "artisan craftsmanship" are up 21% and "vintage accents" up 17%.1

The good news is this doesn't require a gut renovation. Arched doorways, a curved kitchen island, rounded furniture silhouettes, and detailed millwork can all deliver that effect. It's about adding one or two moments of character — not redoing everything.

Photo Credit: Elizabeth Frost Designs
https://pro.houzz.com/pro-learn/blog/sneak-peek-houzz-reveals-11-of-the-top-home-design-predictions-for-2026

Surfaces and Materials That Make a Statement


Photo Credit: Verner Architects; LMB Interiors (Designer); Eric Rorer (Photographer)

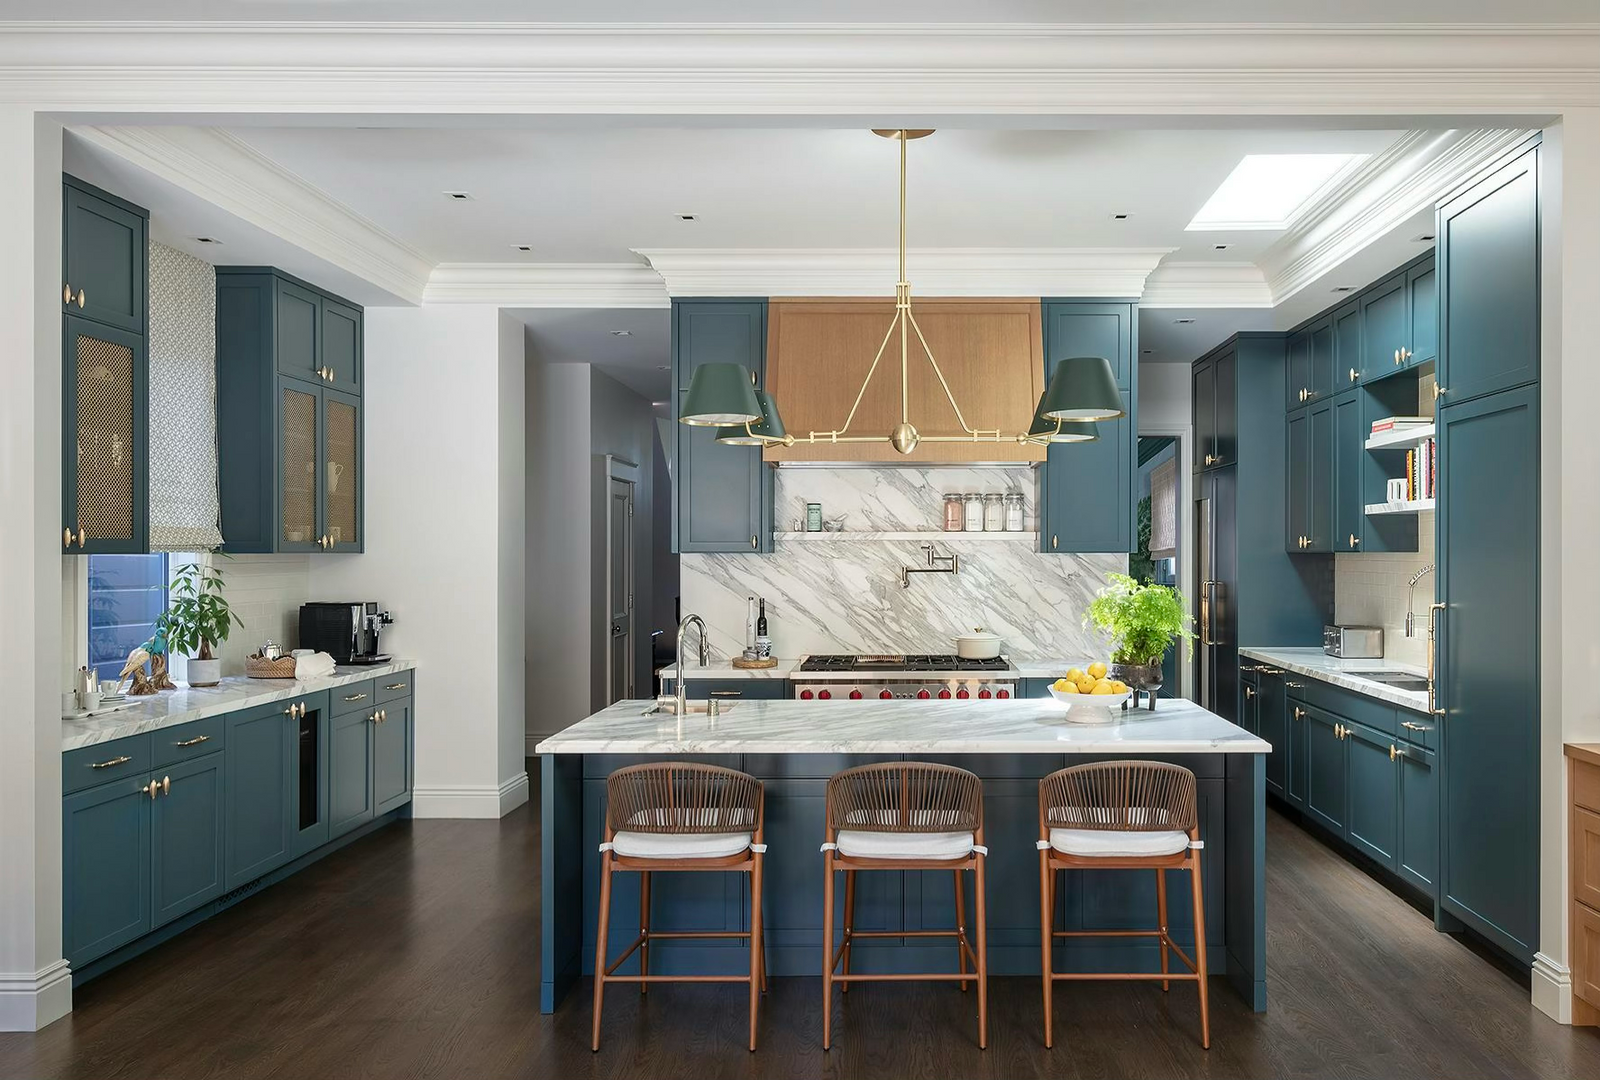
Countertops and backsplashes are no longer meant to blend in. Natural stone — quartzite, marble, and travertine with soft sweeping veining — is being used as a focal point rather than a background. Full-height backsplashes and dramatic stone applications create depth and warmth that photographs beautifully.2 Organic texture is showing up everywhere alongside it: plaster and limewash walls, sculpted surfaces, three-dimensional materials that shift with changing light.

Layered metals — brushed brass paired with matte black and nickel — signal a more evolved, curated take on the mixed-metals trend that's been building for a few years. The goal is intentional, not matched. Each finish feels chosen.

The Kitchen Is Getting Personal

Credit: Leigh Ann Rowe; Builder: OC Builders Group; Designer: Studio Willow

https://pro.houzz.com/pro-learn/blog/2026-houzz-kitchen-trends-article

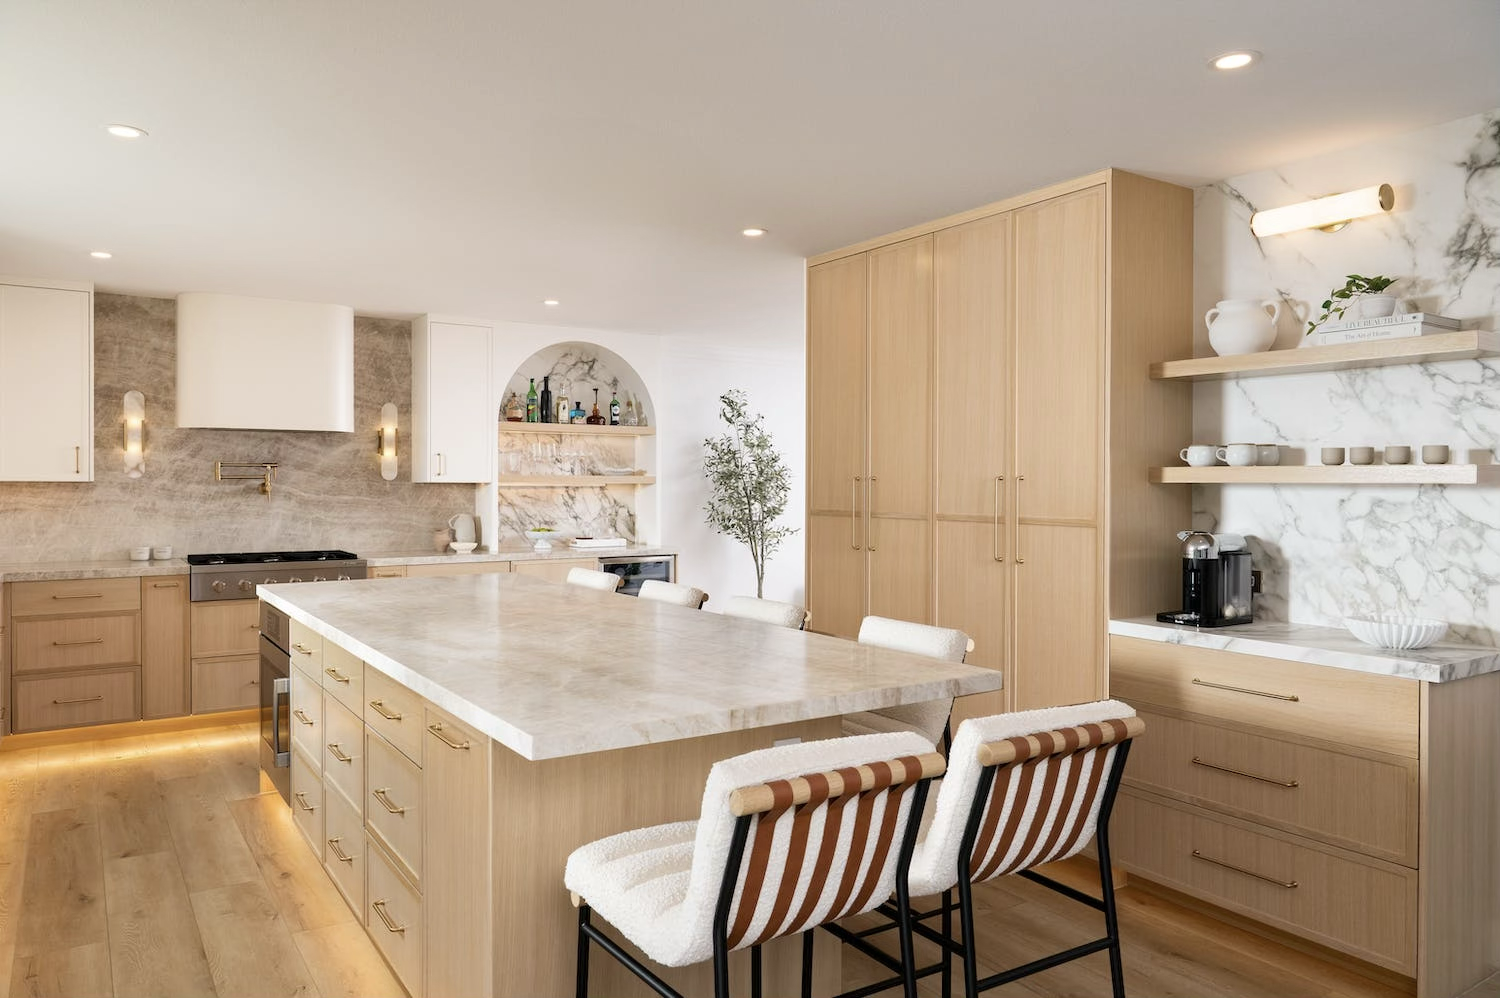
Design professionals are nearly unanimous that the all-white kitchen has run its course.7,10 What's replacing it isn't one look — it's the absence of a default. Warm neutrals, earth tones, and wood-grain cabinetry are taking over from painted finishes, and the transitional style has settled in as the most popular direction, with the farmhouse kitchen continuing to lose ground it's unlikely to recover.5

The bigger shift underneath all of it is personalization. Buyers want to see a kitchen that feels considered — not one that played it safe. A work-in pantry, an unexpected cabinet color, a stone backsplash that runs floor to ceiling: these are the details that make a kitchen feel like it belongs to someone, which turns out to be exactly what buyers are looking for.

Open Concept Grew Up

Open floor plans aren't going away — but buyers no longer want an undifferentiated box. Buyer preferences have shifted toward layouts that offer both flow and definition — spaces that feel connected but serve a clear purpose.4 What's rising is the semi-closed floor plan: subtle architectural separation between the kitchen, dining room, and living areas that maintains connection while creating intimacy. The flexibility of how a home's space is organized now matters more to buyers than the raw square footage it contains.12

Remote work is a big part of why. When your home is also your office, privacy has real value. Dedicated home offices are consistently one of the most requested features this year, and mentions of "reading nooks" — quiet, defined personal spaces — are up 48% in Zillow listing descriptions.1 If you're thinking about selling and you have a defined dining room, a separate office, or distinct living zones, don't apologize for them. Stage and describe each space as intentional. Buyers are looking for purpose, not just square footage.

Homes That Are Designed to Feel Good

One of the quieter shifts in how buyers evaluate homes is the move toward what designers call wellness design — the idea that a home's layout and materials should actively support how you feel in it, not just how it looks. It's less about a single feature and more about an overall sensibility: does this space help you rest, focus, and decompress, or does it just look good in photos?

That sensibility is showing up in listing language in measurable ways — wellness mentions are up 33% year over year, and spa-inspired bathrooms have climbed 22%.1,8 But the concept has expanded well past the primary bath. Biophilic design — bringing in natural light, organic materials, living plants, and visual connections to the outdoors — has become a core consideration because it addresses the same underlying need: buyers want to feel better in their homes.9 So does circadian lighting that shifts with the time of day, and dedicated spaces designed specifically for quiet — a reading corner, a window seat, a nook that actually gets used.

These aren't luxury add-ons anymore. They're showing up in mainstream listings because people are prioritizing how their home makes them feel on a Tuesday afternoon, not just how it presents at a party.

Resilient and Efficient Homes: The Practical Side of 2026 Design

Climate reality is showing up in listing data in a way that's hard to ignore. Features like flood protection, fire-resistant landscaping, and whole-home battery systems are all climbing fast — and 86% of buyers now say it's very important that a home be "climate-proof."1 Zero-energy-ready homes have surged 70% in Zillow listing mentions, with whole-home batteries up 40% and EV charging up 25%.1

Energy efficiency is part of the same conversation. Buyers are evaluating solar readiness, EV chargers, and efficient HVAC systems the same way they evaluate a kitchen renovation — as a financial consideration, not just an environmental one. Utility costs, insurability, and long-term resilience are all factored in. If you're thinking about selling and you have any of these features, make sure they're documented clearly in your listing. Buyers are actively reading for this language, and homes that speak to it stand out.

What's Out

Design trends don't just tell you what to add — they tell you what to address before you list. A few things buyers have clearly moved past:

  • All-gray everything. Functional for a decade, now forgettable. Buyer sentiment has shifted clearly away from both cool gray and stark white as default palettes. Sterile, clinical spaces read as dated now, not clean.2,3

  • The overdone farmhouse look. The aesthetic isn't dead, but the version heavy on purely decorative elements — shiplap for the sake of shiplap, barn doors on every opening — has peaked. What's replacing it is a warmer, more grounded approach leaning on authentic materials over surface-level styling.

  • Themed bonus rooms. "Man cave," dedicated wine rooms, home theaters with no other use — buyers want rooms that flex, not rooms that commit to a single identity. Spaces that can't be repurposed read as liabilities now, not amenities.

  • Two-story foyers. They create a striking visual, but the trade-offs have caught up with them. NAHB data shows 32% of buyers are likely to reject a home with a two-story foyer outright, while only 13% consider it a must-have.6 The energy inefficiency, heat imbalance, and lost usable square footage are no longer worth the entrance moment.

  • Matched-finish everything. Coordinating every fixture, cabinet pull, and faucet to a single metal finish now reads as a 2015 renovation. The shift is toward intentionally layered metals — brushed brass, matte black, and nickel — that feel collected over time rather than sourced from the same catalog page.

  • Open shelving as a kitchen default. What looked fresh a few years ago now reads as high-maintenance and visually noisy to a lot of buyers. The enthusiasm for it has cooled significantly, and the backlash is real enough that agents are recommending sellers address it before listing.11

  • Safe "greige" tile that disappears into the background. Surfaces are meant to make a statement now, not blend in. Full-height backsplashes, dramatic stone, and layered finishes have replaced the disappearing neutral as the standard expectation in well-presented kitchens and baths.

  • Maximalism for resale. Rich, layered, highly personal spaces can be genuinely beautiful to live in — but they're difficult to sell. Buyers need to be able to see themselves in a space. Heavy personalization, bold collections, and visually dense rooms make that harder, which tends to show up in longer days on market and more negotiated offers.

What Changes and What You Leave Alone

Not every item on this list requires a contractor. A $500–$2,000 refresh can meaningfully shift how a home is perceived: paint in a warm current tone, swapping out dated light fixtures, updating hardware from chrome to brushed brass or matte black, adding a limewash accent wall in a key space. These are cosmetic moves — but they change how a home feels, and that feeling is what drives buyer interest from the very first look.

That first look is doing more work than most sellers realize. Warm, textured, layered spaces photograph better than stark white minimalist ones — and since most buyers have already formed a strong impression before they ever step inside, the visual presentation of your home directly affects how fast it moves and what kind of offers it generates.

Buyers are deciding in seconds. The goal is to design for the feeling they get at first scroll — not the trend you were following three years ago.

If you're thinking about preparing your home to sell and want to know which updates are worth making in your specific price range and neighborhood, reach out. That's exactly the kind of conversation that can make a real difference in your results.

Sources

1. Zillow – Spotted on Zillow: Six Home Trends To Follow in 2026

2. Houzz – Sneak Peek: Houzz Reveals 11 of the Top Home Design Predictions for 2026

3. Axios – 2026 home design trends: Zillow and others reveal picks

4. RoylinSells – Are Open Floor Plans Still Popular in Today's Housing Market?

5. Houzz – 2025 U.S. Houzz Kitchen Trends Study

6. NAHB – Two-Story Foyer Trend Stabilizes in 2024

7. Fixr – Kitchen Design Trends Report 2026

8. Fixr – Bathroom Design Trends Report 2026

9. Tami Faulkner Design – Top Custom Home Design Trend 2026

10. NKBA – 2026 Design Trends Report

11. GoBankingRates – 6 Key Design Trends That Are Make-or-Break for Homebuyers in 2026

12. BHGRE – 2026 Design Trends Moving Real Estate

Read
This website may only be used by consumers that have a bona fide interest in the purchase, sale, or lease of real estate of the type being offered via the website. The data relating to real estate on this website comes in part from the MLS® Reciprocity program of the PropTx MLS®. The data is deemed reliable but is not guaranteed to be accurate.